Eli Lilly Q3 Revenue Soars 39% to USD 24.4 Billion as Mounjaro Sales Jump 65% and China Revenue Climbs 69%; Full‑Year Guidance Raised to USD 91–92 Billion
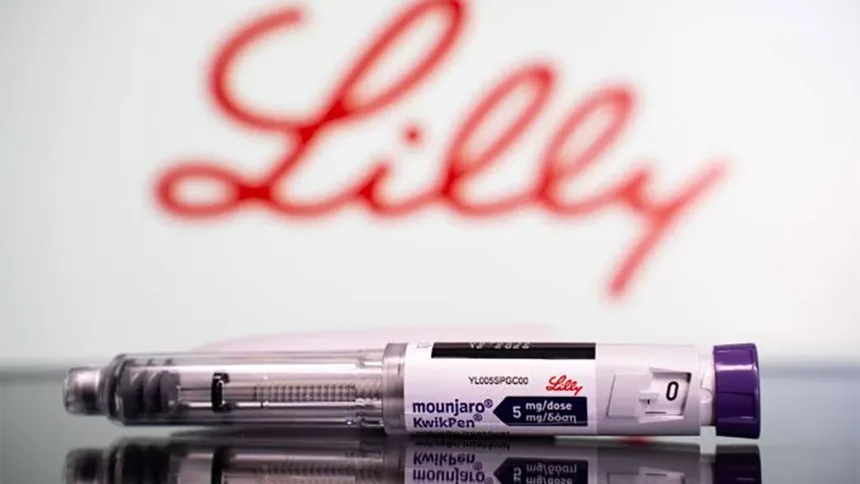
Eli Lilly and Company (NYSE: LLY) reported third‑quarter 2026 worldwide revenue of USD 24.4 billion, up 39% year‑on‑year, driven by strong demand for its diabetes and obesity treatments Mounjaro (tirzepatide) and Zepbound (tirzepatide). The company raised its full‑year revenue guidance to USD 91–92 billion, up from its previous forecast of USD 85–87 billion, citing stronger‑than‑expected sales momentum.
Raised to USD 91–92 bn (prior: USD 85–87 bn) – a USD 5.5 bn midpoint increase
One‑Time Benefits in Q3
≈ USD 900 mn, primarily USD 410 mn in Jardiance collaboration milestones plus favorable rebate and discount estimate adjustments
Product Performance
Product
Q3 2026 Sales
YoY Change
Notes
Mounjaro (tirzepatide) – Worldwide
USD 10.7 bn
+65%
Principal growth driver; U.S. +41% to USD 5.0 bn; International +93% to USD 5.7 bn
Zepbound (tirzepatide) – Worldwide
USD 5.35 bn
+49%
U.S. sales +48% to USD 5.3 bn
Foundayo (orforglipron)
USD 184 mn
New launch
Oral GLP‑1 treatment; continued launches during the quarter
Kisunla (donanemab)
USD 193 mn
+175%
Alzheimer’s treatment
Jaypirca (pirtobrutinib)
USD 228 mn
+59%
Oncology
Newer Immunology/Oncology/Neuroscience Portfolio
Not disclosed
Doubled YoY
Per company Q3 reporting
Geographic Revenue
Region
Q3 2026 Revenue
YoY Change
United States
USD 15.1 bn
+34% (volume +41%)
Outside the U.S.
USD 9.3 bn
+47% (international volume +76%; realized prices −29%)
China
USD 947 mn
+69% (+less than 1% sequentially vs. USD 941 mn in Q2)
Europe
USD 4.46 bn
+27%
Japan
USD 648 mn
+17%
Rest of World
USD 3.21 bn
+90%
Nine‑Month China Trajectory: Revenue from China totaled USD 2.58 billion in the first nine months of 2026, up 75% from USD 1.48 billion a year earlier.
China – Revenue Rises 69% as Reimbursement Weighs on Prices
NRDL Inclusion Effect: The inclusion of Mounjaro on China’s National Reimbursement Drug List (NRDL) in Q1 2026 continued to shape international performance – expanding reimbursed access for type 2 diabetes patients while reducing realized selling prices.
Price Attribution: Lilly attributed the 29% decline in international realized prices primarily to the Chinese reimbursement decision; the company did not disclose separate Mounjaro revenue, prescription volumes, or price changes for China.
Growth Profile: China revenue growth of 69% year‑on‑year to USD 947 million slowed to less than 1% sequentially, indicating the market is settling into a post‑NRDL volume‑for‑price equilibrium.
Market Impact & Outlook
Guidance Leap: The USD 5.5 billion midpoint raise to USD 91–92 billion marks one of the most substantial in‑year outlook increases in large‑cap pharma, cementing Lilly’s position at the center of the obesity and cardiometabolic market.
Volume‑Over‑Price Growth Model: With global volume up 53% against a 15% price decline, Lilly is trading realized price for access and scale – a strategy most visible in China’s NRDL‑driven expansion (+76% international volume).
Tirzepatide Duopoly: Combined quarterly sales of USD 16 billion across Mounjaro and Zepbound underscore tirzepatide’s dominance in type 2 diabetes and obesity care.
Pipeline Breadth Emerging:Foundayo’s oral GLP‑1 launch (USD 184 mn), Kisunla (+175%), Jaypirca (+59%), and a doubling of the newer immunology/oncology/neuroscience portfolio signal diversification beyond incretin biology.
Quality‑of‑Growth Caveat: Approximately USD 900 million of Q3 revenue – including USD 410 million in Jardiance collaboration milestones and rebate/discount adjustments – provided a partial nonrecurring contribution to reported growth.
Forward‑Looking Statements This brief contains forward‑looking statements regarding Eli Lilly’s revenue guidance, tirzepatide demand, oral GLP‑1 launch trajectory, China reimbursement dynamics, and product commercialization. Actual results may differ materially due to risks including pricing and reimbursement pressures, supply capacity constraints, competitive dynamics in the obesity market, foreign‑exchange fluctuations, and one‑time revenue items not recurring in future periods. Figures are as reported in the company’s Q3 2026 results and Form 10‑Q.-Fineline Info & Tech
Insight, China's Pharmaceutical Industry Fineline Info & Tech is a comprehensive global pharmaceutical database that spans the entire product lifecycle. Its mission is to equip professionals and executives across all sectors of the life sciences industry with a standardized data language, offering a holistic view of the Chinese pharmaceutical competitive landscape. Flcube.com furnishes critical data essential for informed decision-making, drawing on global industry news, policy insights, competitive intelligence, and advanced analytical tools.