
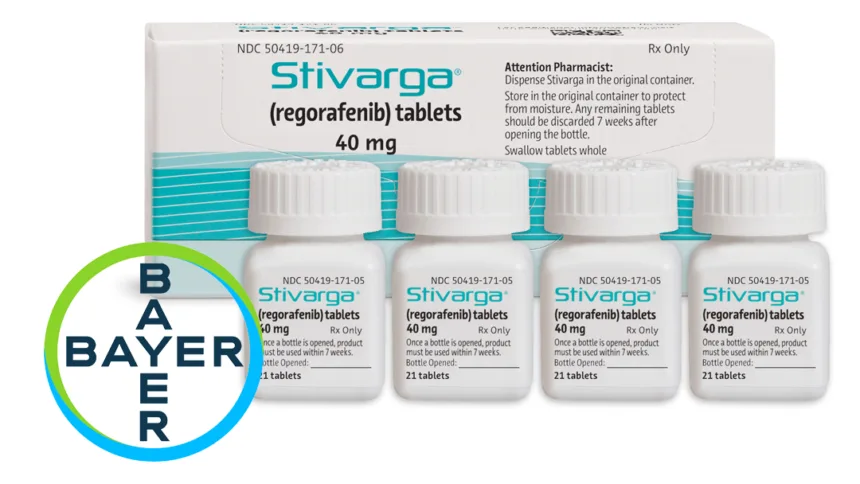
Grünenthal GmbH announced an agreement with Bayer AG (ETR: BAYN) to acquire Stivarga (regorafenib) for up to €375 million, bringing the approved oral multikinase inhibitor – marketed in more than 90 markets worldwide for metastatic colorectal cancer, hepatocellular carcinoma and gastrointestinal stromal tumours (GIST) – into the Grünenthal portfolio.
Contents
Deal Snapshot
| Item | Detail |
|---|---|
| Acquirer | Grünenthal GmbH (private, Germany) |
| Seller | Bayer AG (ETR: BAYN) |
| Asset | Stivarga (regorafenib), oral multikinase inhibitor |
| Consideration | Up to €375 million |
| Conditions | Customary closing conditions, including approval by the relevant regulatory authorities |
| Expected Closing | End of 2026 or early 2027 |
| Loss of Exclusivity | Anticipated 2029 in the EU and 2030 in the U.S. |
| Deal Rationale Detail | Payment structure (upfront vs contingent) – not disclosed |
Product Profile – Stivarga (Regorafenib)
- Modality: An oral multikinase inhibitor, offering a convenient pill‑based option across three solid‑tumor indications.
- Approved Indications: Treatment of patients with metastatic colorectal cancer (mCRC), hepatocellular carcinoma (HCC), and gastrointestinal stromal tumours (GIST) who have already been treated with, or who cannot be given, other available treatments – a later‑line positioning across all three tumor types.
- Global Footprint: Approved and available in more than 90 markets worldwide, providing an established commercial base and recognized brand equity in oncology.
- Franchise Heritage: Originally developed and commercialized by Bayer, Stivarga has served as a mainstay of later‑line therapy in gastrointestinal oncology for over a decade.
Transaction Structure & Timeline
- Consideration Cap: The up to €375 million headline value frames the maximum economics of the transaction; the split between upfront payment and contingent amounts – not disclosed.
- Regulatory Path: Completion remains subject to customary closing conditions, including approval by the relevant regulatory authorities.
- Closing Window: The acquisition is expected to close by the end of 2026 or early 2027.
- Strategic Logic: For Grünenthal, the deal adds a diversified, already‑marketed oncology franchise; for Bayer, the divestiture monetizes a late‑lifecycle asset ahead of generic entry.
Market Impact & Outlook
- Exclusivity Runway: With loss of exclusivity anticipated in 2029 in the European Union and 2030 in the United States, the transaction is effectively a valuation of Stivarga’s remaining protected‑market cash flows plus post‑LOE brand resilience.
- Portfolio Transformation for Grünenthal: Acquiring a global oncology brand spanning mCRC, HCC and GIST meaningfully expands Grünenthal’s therapeutic reach beyond its established pain franchise.
- Divestiture Discipline at Bayer: The sale continues Bayer’s pattern of pruning non‑core, late‑lifecycle pharmaceutical assets to concentrate capital on priority pipelines.
- Later‑Line GI Oncology Demand: In previously treated or treatment‑ineligible mCRC, HCC and GIST populations, oral multikinase inhibitors remain a cornerstone of care, supporting sustained demand through the exclusivity window.
- Post‑LOE Strategy: How Grünenthal manages generic competition after 2029–2030 – including lifecycle management and pricing strategy – will shape the deal’s ultimate return; no such plans were disclosed.
Forward‑Looking Statements
This brief contains forward‑looking statements regarding transaction closing, regulatory approvals, exclusivity timelines, and post‑acquisition commercial performance of Stivarga. Actual results may differ materially due to risks including closing conditions, competitive dynamics, generic entry timing, and reimbursement developments.-Fineline Info & Tech