
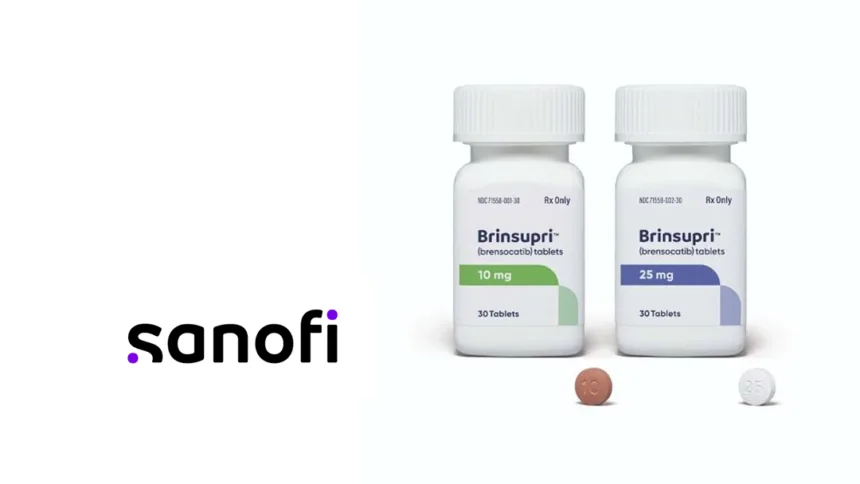
Reports emerged on 19 November 2026 that Sanofi (NASDAQ: SNY) may be considering an acquisition of Insmed, the developer of the novel respiratory medicine Brinsupri (brensocatib) — the first dipeptidyl peptidase 1 (DPP1) inhibitor to reach the U.S. market. With Insmed’s potential valuation currently exceeding USD 30 billion, a completed buyout could rank among the largest M&A deals in the pharmaceutical industry since Pfizer’s USD 43 billion acquisition of Seagen in 2023.
Transaction Snapshot – Report
| Item | Detail |
|---|---|
| Reported Acquirer | Sanofi (NASDAQ: SNY) |
| Potential Target | Insmed |
| Status | Reported under consideration – not confirmed by either party |
| Key Asset | Brinsupri – first‑in‑class DPP1 inhibitor for non‑cystic fibrosis bronchiectasis (NCFBE) |
| Implied Valuation | Insmed potential valuation exceeding USD 30 billion |
| Deal Scale Context | Potentially one of the largest pharma M&A transactions since Pfizer–Seagen (USD 43 billion, 2023) |
Asset Profile – Brinsupri (Brensocatib)
- Molecule: A novel respiratory medicine and the first dipeptidyl peptidase 1 (DPP1) inhibitor to reach the U.S. market.
- FDA Approval: Approved in August 2025 for the treatment of non‑cystic fibrosis bronchiectasis (NCFBE) in adults and children aged 12 and older.
- Indication Significance: NCFBE is a chronic, progressive lung disease historically without approved disease‑modifying therapy — Brinsupri’s 2025 approval created a new treatment category in respiratory medicine.
- Strategic Fit: An acquisition would give Sanofi a first‑in‑class respiratory franchise, complementing its established immunology and specialty‑care portfolios.
Commercial Performance – Brinsupri Sales
| Metric | Figure |
|---|---|
| Global Sales, First Nine Months of 2026 | Slightly exceeded USD 917 million |
| Full‑Year 2026 Guidance | USD 1.35 billion to USD 1.4 billion |
| Commercial Trajectory | Blockbuster‑scale ramp within ~16 months of FDA approval |
According to Insmed, global sales of Brinsupri slightly exceeded USD 917 million in the first nine months of 2026, and the company now expects total annual sales of the drug to reach USD 1.35 billion to USD 1.4 billion this year — an unusually rapid commercial ramp for a first‑in‑class respiratory asset.
Market Impact & Outlook
- M&A Landscape: A potential Sanofi–Insmed transaction would be among the largest pharmaceutical M&A deals since Pfizer’s USD 43 billion acquisition of Seagen in 2023, reinforcing the industry’s reliance on billion‑dollar takeovers to secure differentiated, rapidly growing assets.
- Valuation Anchor: With Insmed’s potential valuation exceeding USD 30 billion, Brinsupri’s sales trajectory and first‑in‑class status are the primary drivers of the target’s premium.
- For Sanofi: Acquiring a first‑in‑class DPP1 inhibitor with blockbuster momentum would strengthen Sanofi’s respiratory and immunology growth profile at a time of intensifying competition for late‑stage commercial assets.
- Cautionary Note: The report is unconfirmed; no agreement has been announced, and discussions — if occurring — may or may not result in a transaction. Terms, timing and structure were not disclosed.
Forward‑Looking Statements
This brief contains forward‑looking statements regarding a reported potential acquisition that has not been confirmed by Sanofi or Insmed, as well as statements regarding Brinsupri sales expectations and market potential. Actual results may differ materially; no assurance can be given that any transaction will be announced or completed, and risks include negotiation outcomes, regulatory review, competitive dynamics and commercial performance.-Fineline Info & Tech